
DXC & YEO team up on continuous bank identity checks
Fri, 30th Oct 2026 (Today)
DXC and YEO have formed a partnership focused on identity assurance for financial services, centred on digital banking and payments.
The companies will combine DXC's financial services expertise with YEO's Continuous Facial Recognition software development kit, designed to verify identity throughout an active digital session rather than only at login.
The tie-up addresses a challenge for banks and payments groups as more customer activity moves online. Traditional authentication methods may confirm who starts a session, but not necessarily that the same person remains in control throughout the interaction.
That issue has drawn greater attention as financial institutions contend with account takeover, session hijacking and AI-enabled impersonation. For regulated firms, knowing who is present during a digital exchange has implications for fraud controls, customer trust and accountability.
DXC has an established position in technology services for financial institutions, while YEO seeks to expand its identity assurance technology in sectors where verification and auditability matter. The partnership will initially focus on financial services, where compliance demands and customer expectations are pushing banks to review how they manage digital identity.
Authentication gap
YEO's technology is built around what it calls continuous identity assurance. In practice, this means using facial recognition during a session to check whether the authenticated user remains present, adding another layer to measures such as behavioural biometrics and device intelligence.
The approach reflects a wider debate in financial services over whether one-time checks at onboarding or login are still sufficient as fraud techniques evolve. Banks have invested heavily in customer authentication, but criminals have also adopted new tactics, including the use of artificial intelligence to support impersonation attempts.
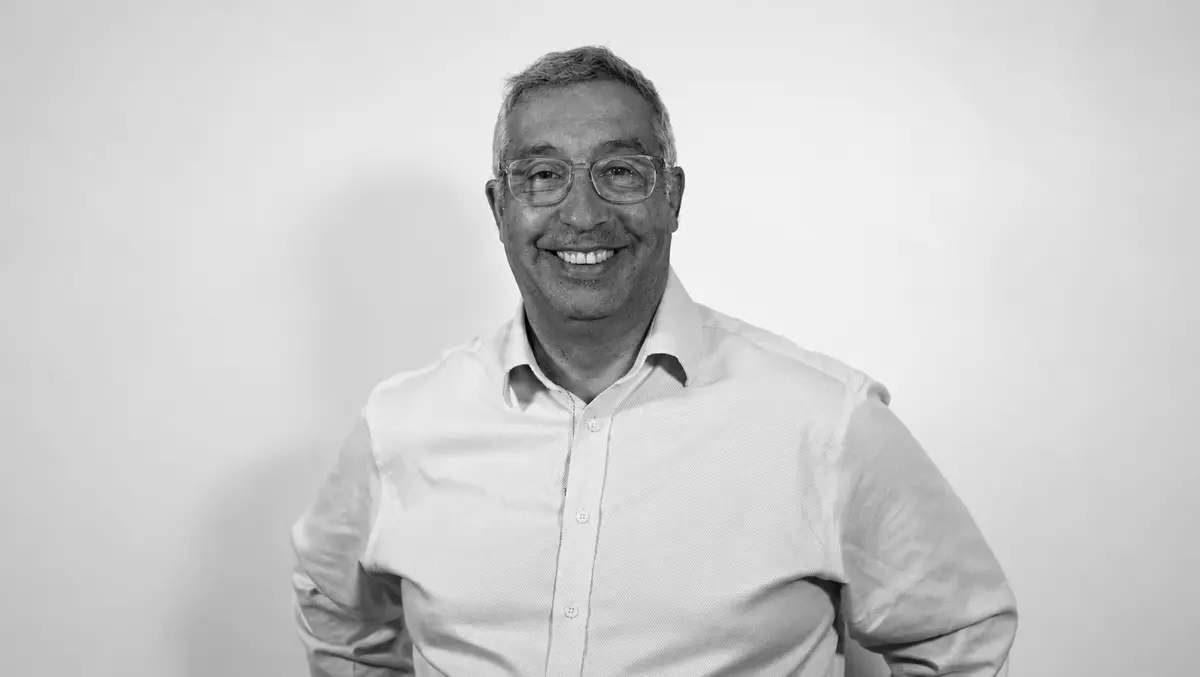
Christo Conidaris, Chief Revenue Officer at YEO, said: "AI-enabled fraud and digital impersonation are changing the nature of the threat facing financial institutions. Banks have invested heavily in securing the point of login, but authentication alone cannot guarantee that the same individual remains in control throughout a digital interaction. That is a significant gap, particularly when high-value transactions and sensitive customer information are involved.
"The next generation of FinTech fraud prevention will depend on a layered approach, combining behavioural biometrics, network and device intelligence with continuous identity assurance. Each provides a different piece of the puzzle, but together they offer a more complete picture of who is behind a digital interaction.
"Our partnership with DXC brings together its extensive financial services expertise and YEO's Continuous Facial Recognition technology to address this challenge. Together, we want to help financial institutions move beyond one-time authentication towards a model of continuous trust, strengthening security throughout the customer journey without introducing unnecessary friction for legitimate users."
Sector pressure
Financial institutions are balancing two demands that do not always sit easily together: tighter fraud controls and a smoother digital experience for customers. Mobile banking, digital payments and remote servicing have raised the stakes, particularly in areas involving high-value transactions or access to sensitive personal data.
As a result, banks are looking more closely at layered security models that go beyond passwords, one-time passcodes and static biometric checks. Behavioural monitoring, device profiling and network signals are already used in some environments to assess risk during a session. Continuous facial recognition would sit alongside those tools rather than replace them.
YEO said its software uses on-device biometric processing, a point likely to matter for institutions concerned about privacy, data handling and regulatory scrutiny. The company already markets its technology to sectors including government, insurance, cybersecurity and professional services, but the new partnership places financial services at the centre of its latest commercial push.
For DXC, the agreement adds another identity-focused offering to its work with banks and other financial firms undergoing digital change. As institutions continue to automate customer interactions and expand digital-first services, the need to prove identity not just at entry points but throughout an interaction is becoming more important.
The partnership is intended to help banks and financial institutions test new ways of securing customer interactions while maintaining digital journeys that do not create unnecessary barriers for legitimate users.
The collaboration reflects a broader market shift towards continuous verification models as firms reassess how trust is maintained online when fraud methods are becoming more sophisticated, and identity claims are harder to validate in real time.